INSTALLMENT HOUSE IN LAHORE: COMPLETE BUYER’S GUIDE
Introduction
The cash flow reality of buying a house in Lahore is stark: most families can’t save 20–30 years to afford one outright. Installment properties solve this by spreading the cost over 2–4 years, making homeownership accessible without depleting your savings today.
This guide walks through what installment properties actually are, how payment plans work, what to check before committing, and why 2026 is reshaping this market. You’ll understand the real risks, the safeguards that matter, and whether this path fits your situation.
Why Installment Properties Are Reshaping Lahore’s Market
Cash Flow Reality, Not Imagination
An installment property lets you live in—or rent out—a completed home while paying for it over time. Instead of saving 2–3 crore upfront, you might pay 20–30% down and then monthly installments. For a 2 crore property with a 25% down payment (50 lakh), your monthly commitment on a 3-year plan runs approximately 4.5–5 lakh per month far more manageable than the lump sum.
This matters because it lets you enter the property market when you need it, not when you’ve saved enough.
Why Developers Offer Installments
Developers benefit from steady cash flow and faster sales. You benefit from affordable entry. It’s not charity—it’s market economics. When fewer buyers can pay cash, developers who offer flexible terms capture market share.
The critical difference: possession-linked installments (where you pay as construction completes) protect you better than pre-possession installments (where you pay first, receive later). Possession-linked is now standard at reputable developers.
2026 Market Shift: Possession Now Comes First
For the first time in years, buyers are prioritizing possession-backed installments over open-ended commitments. The 2024–2025 corrections taught hard lessons: promises matter less than guaranteed timelines.
Developers showing completed work and fixed possession dates attract serious capital. This shift has created a clear separation: transparent developers with track records thrive; vague ones stall.
Investment Safety Through Possession Dates
Installment buying isn’t inherently risky. The risk comes from buying from unverified developers. Possession-linked installments with LDA-approved land and written guarantees are legally enforceable.
When your payment is tied to actual construction progress—not years-away promises—your money moves in sync with their work. You’re not funding a developer’s other projects; you’re funding your property.
Types of Installment Properties: Finding Your Match
By Size: Marla and Monthly Cost
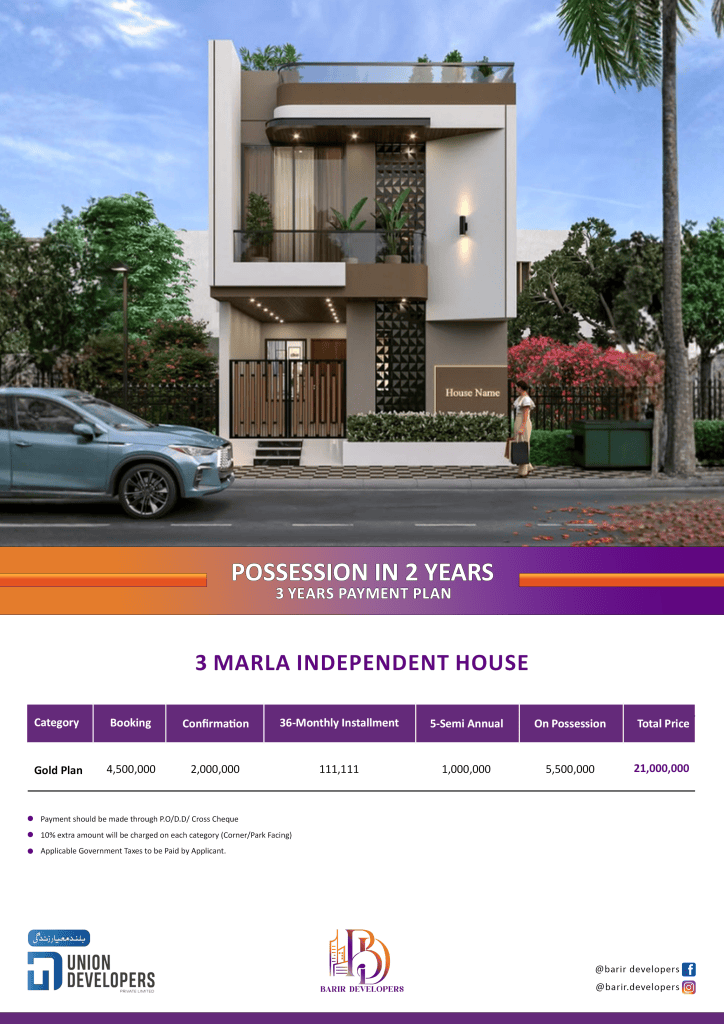
3-Marla Houses: Entry-level in established schemes, PKR 35–55 lakh base price, approximately 1–1.5 lakh monthly on installment. Appealing to first-time buyers and investors targeting rental markets.
4-Marla Townhouses: Growing segment, PKR 50–80 lakh, roughly 1.5–2.2 lakh monthly. Balanced space-to-cost ratio; popular with young families upgrading from rented apartments.
5-Marla Independent Houses/Townhouses: Lahore’s most demanded size, PKR 75–130 lakh depending on location and finish, approximately 2–3 lakh monthly. Offers separation and privacy while remaining affordable compared to larger plots.
8-Marla & 10-Marla: Premium segment, PKR 150–300+ lakh, monthly payments 3.5–6 lakh+. Targets investors and established families seeking longer-term appreciation.
The base price alone doesn’t determine affordability compare monthly installment amounts against your actual cash flow, not the headline figure.
By Location: Scheme Tier Matters
Tier-1 (Premium Appreciation Potential): Bahria Town Lahore, DHA Phases 5–7, Lake City. Established amenities, strong resale demand, 15–25% higher prices. Overseas buyers concentrate here.
Tier-2 (Balanced Growth): Union Town, Central Park, Park View. Maturing schemes with solid infrastructure, moderate price appreciation, practical for mid-range buyers.
Tier-3 (Emerging/Riskier): Schemes on Raiwind Road, Sargodha Road, outlying areas. Lower prices, higher upside potential, but dependent on future development. Longer holding periods before liquidity.
Proximity to main roads (Canal Road, Ferozepur Road, MM Alam Road) and existing amenities (schools, hospitals, shopping) commands 10–20% premiums on identical properties in less-connected areas.
By Property Type: Independence vs. Community
Independent Houses: Full privacy, own entrance, no shared walls. Premium pricing; slower resale in some markets. Best if you plan to stay long-term.
Townhouses: Shared walls, community amenities, lower maintenance burden. Faster resale, active rental markets. Practical for investors.
Plots: Raw land, lowest upfront cost, but you handle construction separately. Riskier for first-time buyers; better for developers or experienced investors.
New Builds vs. Ready-to-Shift
New Builds (Under Construction): Lower prices, longer possession timeline (18–36 months), possession-linked installments possible. Risk: construction delays. Benefit: lock in today’s price.
Ready-to-Shift (Completed): Immediate possession, no construction risk, higher price. Good if you need to occupy immediately; limits your negotiating position.
Payment Plans Explained: How Monthly Installments Actually Work
Standard Installment Structure
A typical 3-year installment plan breaks down like this:
- Down Payment: 20–30% (paid upfront)
- Possession Installments: Months 1–18 (during construction)
- Post-Possession Installments: Months 19–36 (after you receive keys)
Some developers offer variations: 2-year plans (higher monthly payments), 4-year plans (lower monthly amounts), or payment holidays (3–6 months off mid-way).
Real Monthly Calculations
For a 2 crore property:
| Down Payment (25%) | 50 lakh |
| Remaining Balance | 1.5 crore |
| Months to Pay | 36 (3 years) |
| Monthly Installment | ~4.17 lakh |
Add 5–10% for processing/closing costs. Your actual monthly payment: 4.3–4.6 lakh.
This doesn’t include property tax (1–2% annually) or transfer fees (5% at registration).
Possession Timeline vs. Payment Timeline
Possession-linked installments tie your payment schedule to construction milestones:
- Months 0–3: Foundation complete, you pay 15–20% of balance
- Months 4–12: Structure complete, you pay another 30–40%
- Months 13–18: Finishing work, final 40–50% due
- Month 18–19: Possession keys handed over
This is safer than pre-possession plans where you pay everything before construction even breaks ground.
Hidden Costs: Interest, Markup, Processing
Most installment plans include a 5–12% markup (not called “interest,” but it’s baked into the monthly amount). Some developers charge processing fees (20,000–50,000 PKR). Document all charges in writing before signing.
Banks offering installment loans add their own interest on top, though this is separate from the developer’s plan.
What Happens if You Miss a Payment
Grace period: typically 15–30 days. After that, late fees apply (1–2% per month). Repeated defaults (3+ months) can trigger:
- Loss of possession right
- Forfeiture of down payment
- Cancellation of agreement
This is why installment commitments must fit your real cash flow, not optimistic projections.
Critical Checks to Run Before You Commit
Developer Credentials: Verify, Don’t Assume
Before signing, answer these questions:
- How long has the developer been operating? (5+ years ideally; check PEC registration for engineers)
- What projects have they completed? Visit finished properties. Talk to residents. Ask how many units were delayed or never delivered.
- Are they current on tax filings? Request FBR/EOBI documentation.
- Do they have LDA/CDA approvals? For Union Town developments, verify with Lahore Development Authority.
[FACT-CHECK REQUIRED: Specific Barir Developers completion record and timeline for Pine Homes should be verified against company records or third-party sources before claiming in promotional context.]
Land Ownership & LDA Approval: Non-Negotiable
Ask for:
- Original title deeds (not photocopies)
- LDA approval letter for the scheme
- NOC from any relevant authority (municipal, water, power)
- Proof the developer owns the land free of encumbrance
If these documents aren’t provided in writing, walk away. This is the single biggest risk factor.
Possession Timeline: Get It in Writing
The possession date should be in your agreement with penalties for delay built in. Standard clauses: if the developer is 6+ months late, you can withdraw and recover your down payment plus 8–12% interest.
Vague language like “possession will be given in 2026” is not sufficient. Demand a specific month and quarter.
Payment Plan Terms: Flexibility Matters
Verify:
- Exact monthly amount (fixed or variable?)
- Due date each month
- Grace period for late payments
- Whether you can make advance payments without penalty
- Option to adjust payment schedule if circumstances change
Inflexible terms create financial stress when life circumstances shift (job loss, medical emergency). Transparent developers offer flexibility; evasive ones don’t.
Possession-Based vs. Full-Payment: Which Protects You Better
| Possession-Linked | Full Pre-Payment |
| Payment tied to construction progress | All funds paid before possession |
| Developer incentivized to complete | Developer has less pressure to finish |
| Risk: construction delays | Risk: never receive possession |
| Standard now; preferred by buyers | Increasingly rare for reputable developers |
Always choose possession-linked when available.
Legal Documentation: Red Flags
Before signing, ensure:
- Agreement is on stamp paper (not plain paper)
- Agreement is registered at the sub-registrar office
- You receive a certified copy
- Language is clear (no ambiguous terms like “approximately” for possession date)
- Clauses on dispute resolution and jurisdiction are specified
Have a property lawyer review it (5,000–15,000 PKR for legal review). This is not negotiable for properties over 1 crore.
Current Market Trends 2026: Why Timing Matters
The Possession-First Preference
For the first time in years, buyers are prioritizing possession-backed installments over open-ended commitments. The 2024–2025 market corrections taught hard lessons: promises matter less than guaranteed timelines.
Developers who can show completed work and fixed possession dates—not future projections attract serious capital. This is why possession-linked plans now dominate inquiry boards at major developers.
Which Schemes Are Moving Units
Established schemes continue to lead: Bahria Town Lahore, DHA Phase 5, Lake City, and Union Town remain the preference for 3-to-5-marla buyers. Newer schemes in the Raiwind and Sargodha Road corridors attract investors betting on long-term appreciation but these carry higher risk and longer holding periods.
The consistent pattern: proximity to main roads and existing amenities commands 10–20% premiums on identical properties in less-connected areas.
Overseas Pakistani Interest Accelerating
Overseas Pakistanis and NRO/PRO holders continue increasing property portfolio allocations to Lahore. Improved remittance pathways have made installment buying more accessible for families abroad. This segment now represents an estimated 25–35% of qualified inquiries at premium schemes.
[FACT-CHECK REQUIRED: Current remittance ease and NRO/PRO regulations for 2026 should be verified against State Bank of Pakistan guidance.]
Payment Flexibility as the Competitive Advantage
Developers offering 3-to-4-year stretched installments versus the traditional 2-year model report higher conversion rates. Fewer families can commit to 4–5 lakh monthly payments on premium properties. Schemes offering payment holidays, post-possession flexibility, and restructuring options capture market share faster.
This trend reflects buyer reality: cash flow constraints drive decisions more than investment returns.
Why Barir Developers Stands Out in This Shifting Market
Proven Delivery, Not Promises
Barir’s completed projects including operational properties in Union Town—serve as the confidence foundation that buyers increasingly demand. When you’re committing monthly payments over 3–4 years, seeing finished units and actual residents matters.
This isn’t marketing; it’s the verification step every serious buyer should perform. Barir’s track record provides that proof.
Transparent Terms on Installment Plans
Their installment offerings on Pine Homes (4-marla and 5-marla townhouses in Union Town) follow the possession-linked structure buyers now prioritize: clear possession timelines, fixed monthly amounts, and defined payment windows. No hidden restructuring mid-project. Payment schedules spell out specific dates information competitors often bury or leave vague.
Local Market Knowledge Translates to Practical Terms
Operating in Union Town for years gives Barir direct insight into buyer needs, financing patterns, and scheme performance. They understand the difference between what buyers say they want and what their cash flow actually allows. This shapes payment offerings that work.
Next Steps If You’re Ready
If you’re serious about installment buying in Lahore, the next step is straightforward: compare specific properties against the verification criteria in this guide. Tour completed units. Review payment terms. Ask for possession guarantees in writing.
Schedule a consultation with Barir Developers or visit Pine Homes property listings to see current installment options in Union Town.
Frequently Asked Questions
Are installment properties in Lahore actually safe to buy?
Yes, if you verify the developer and follow the checklist in this guide. The risk isn’t installment buying itself it’s buying from unverified developers. Possession linked installments with LDA-approved land and written possession guarantees are legally enforceable. Safety comes from developer track record and transparent terms, not payment structure.
How long does it actually take to get possession?
Standard timelines range from 18–36 months depending on construction stage. Possession-linked installments tie your payments to actual construction milestones, which means possession happens when the developer completes the unit not years after you’ve finished paying. Always demand the specific possession date in your agreement, not estimates.
Can I rent out the property while I’m still paying installments?
In most cases, yes but verify your developer’s terms. Some schemes allow rental income after possession; others have restrictions during the payment period. If rental income is part of your financial plan, confirm this in writing before committing.
What happens if I miss an installment payment?
Most agreements allow 15–30 days grace before penalties apply (typically 1–2% per month). Repeated defaults (3+ months) can result in loss of possession rights or forfeiture of your down payment. If cash flow becomes tight, contact your developer immediately many offer restructuring rather than cancellation.
When is the best time to buy an installment property?
When you’ve verified a specific property against the criteria in this guide not based on market timing. Installment buying removes the “wait for prices to drop” pressure because you’re locking in today’s price over tomorrow’s payments. The best time is when you’ve found the right property, verified the developer, and confirmed the payment plan fits your actual budget.
Final Thoughts
Installment buying is reshaping Lahore’s real estate market because it reflects financial reality: most buyers can’t pay cash, but they can afford monthly commitments. The shift toward possession inked installments with transparent developers makes this path safer than it once was.
The critical steps remain unchanged: verify the developer, confirm possession guarantees in writing, understand your monthly cash flow, and review legal documentation. These aren’t optional they’re the difference between a smart investment and a financial trap.
The properties are real. The market is moving. The safeguards exist. Now it’s your job to apply them.