Nov 8, 2026 · @Usama
By [Usama Saleem],
Most families who want an independent house run into the same problem: the house fits their life, but the full price doesn’t fit their savings. An independent house payment plan in Lahore closes that gap. You pay a booking and confirmation amount first, then monthly installments and larger semi-annual installments, and a final on-possession payment when the house is handed over.
Barir Developers sells its 3 and 5 Marla independent houses in Union Town, Lahore, on 2-year plans that range from Rs 1.9 crore to Rs 3.5 crore, with possession stated at 1.5 years. This guide uses those published figures to show how much cash you need at the start, what the plan really costs each month, how an independent house compares with a townhouse, and what to check before you sign.
Barir’s independent house plans at a glance
| House | Total price | Booking + confirmation | Monthly installment (24 months) |
| 3 Marla, Union Town Phase IV | Rs 1.9–2.25 crore | Rs 50 lakh | Rs 2.2–2.8 lakh |
| 3 Marla, Union Town | Rs 2.0–2.3 crore | Rs 50–60 lakh | Rs 2.5–3.0 lakh |
| 5 Marla, Union Town | Rs 3.0–3.5 crore | Rs 60 lakh | Rs 3.5–4.5 lakh |
Ranges cover the Bronze, Silver and Golden plans for each house. Source: Barir Developers’ published payment plans, November 2026. Your signed payment schedule is the final word on every figure.
Want the exact schedule for one house? See the live payment plans or book a site visit to go through it with the sales team.
What Is an Independent House Payment Plan?
An independent house payment plan is a written schedule, agreed with the builder, that lets you pay for a standalone house in stages instead of all at once. Each stage has a fixed amount and a due point: booking, confirmation, a run of monthly installments, a few larger semi-annual installments, and a final payment at possession. Add them all up and you get the total price.
The structure is simple. The details decide whether a plan stays comfortable for two years or starts to strain your budget halfway through.
What “independent” means here. An independent house is the whole house on its own plot: the structure, the roof and the land under it belong to one owner. A townhouse or floor-wise unit is different. You buy one floor of a shared building, and these units usually cost less. Plenty of Union Town listings sold on installments are floor units, so check what kind of property a plan covers before you compare prices. For a city-wide look at sizes and building costs, see our guide to independent houses in Lahore.
How it differs from a bank loan. With a developer plan, you pay the builder directly on a fixed schedule; on Barir’s current plans, the full price is cleared in 2 years. With bank home finance, which people often describe as buying a house on installment through a bank, the bank pays the seller and you repay the bank, usually over many years. Buyers living abroad have a third route through the State Bank’s Roshan Digital Account, covered later in this guide.
| Developer payment plan | Bank home finance | |
| Who you pay | The builder, directly | The bank, after it pays the seller |
| How long it runs | Set by the builder (2 years on Barir’s current plans) | Usually many years, set by the bank |
| Main checks before you start | The builder’s approvals, documents and payment terms | Your income and eligibility, and the bank’s valuation of the property |
Why buyers use one. You commit with a fraction of the price and spread the rest over two years, instead of saving the whole amount before you buy. The trade-off is discipline. The semi-annual and possession payments are large, and they fall due on fixed dates whether or not your month went to plan.
If you’re still choosing the house itself, Barir’s guide to 3 and 5 Marla independent houses on installments in Union Town covers sizes and location in detail.
How Barir’s Payment Plan Works, Step by Step
All nine of Barir’s independent house plans follow the same five steps. Only the amounts change from house to house and from tier to tier.
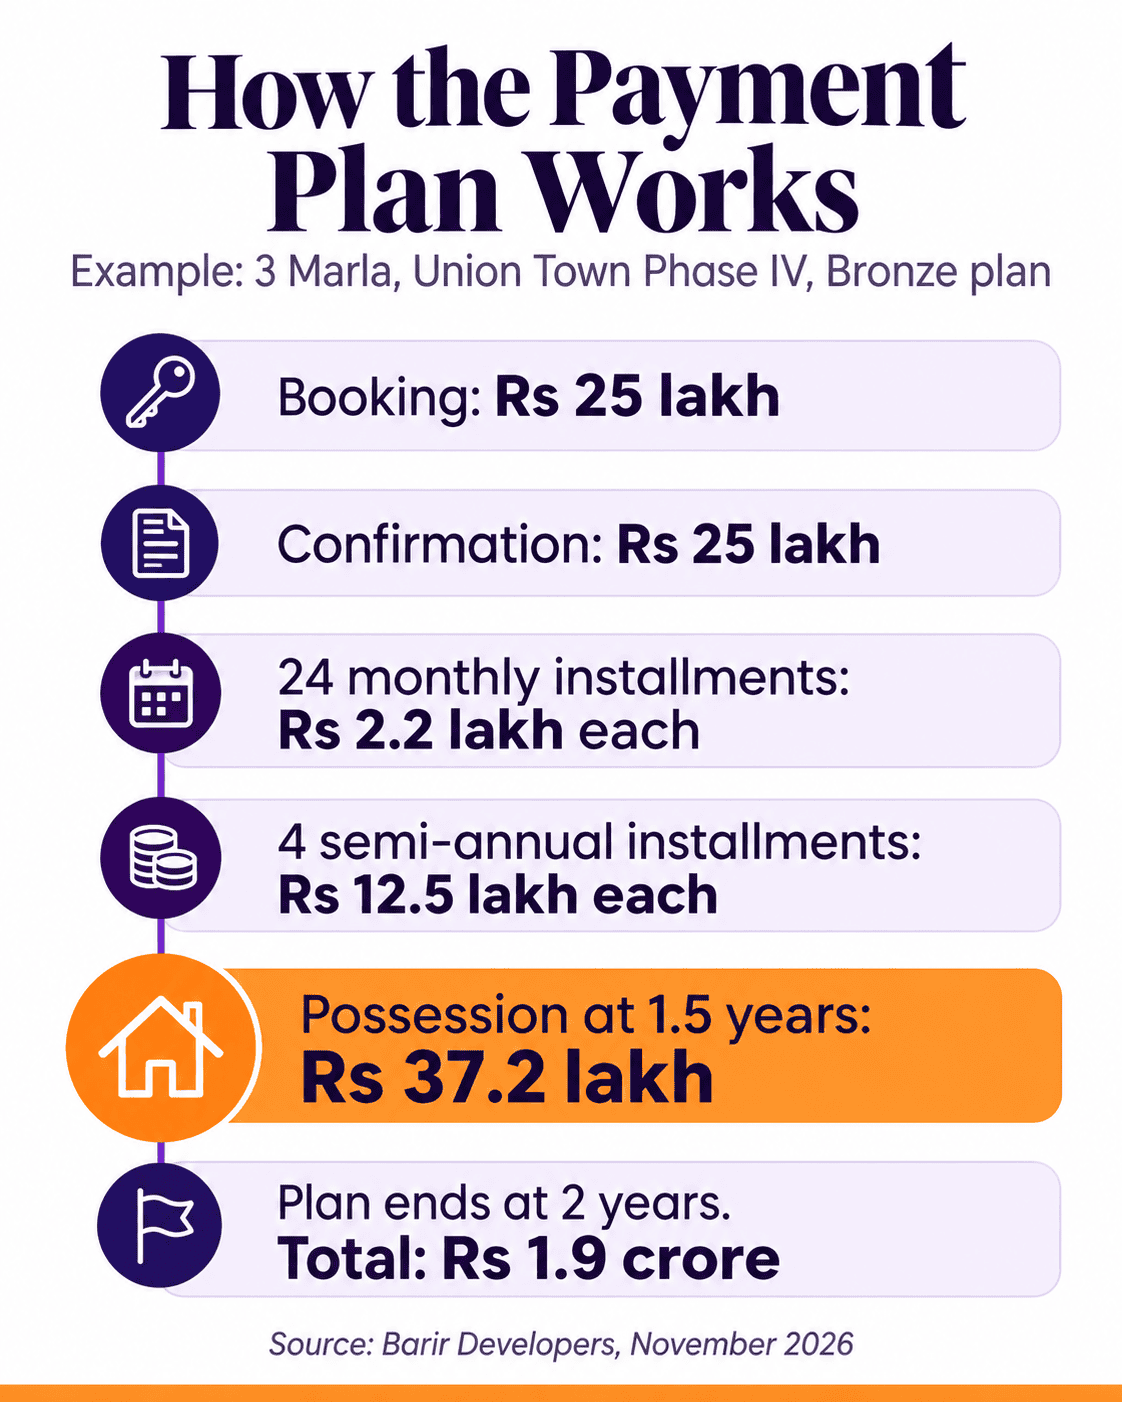
- Booking. The first payment, made when you reserve a house. It is Rs 25 lakh on most 3 Marla plans, and Rs 30 lakh on the 3 Marla Golden plan in Union Town and on every 5 Marla plan.
- Confirmation. A second payment, the same size as the booking. Together, booking and confirmation work as your down payment: Rs 50 lakh or Rs 60 lakh, which is 17% to 26% of the total price. Barir’s townhouse plans list confirmation as due one month after booking, but the independent house plans don’t show the timing.
- 24 monthly installments. The steady part of the plan, paid every month for two years: Rs 2.2 lakh to Rs 3 lakh on 3 Marla plans and Rs 3.5 lakh to Rs 4.5 lakh on 5 Marla plans.
- 4 semi-annual installments. Four larger payments, one every six months, often called half-yearly or balloon payments. They are Rs 12.5 lakh to Rs 14 lakh each on 3 Marla plans and Rs 25 lakh each on 5 Marla plans. On the 5 Marla Bronze plan, the four semi-annual payments come to Rs 1 crore, more than all 24 monthly installments put together (Rs 84 lakh).
- On-possession payment. The final amount, due when the house is handed over: Rs 37.2 lakh to Rs 51.8 lakh on 3 Marla plans and Rs 56 lakh to Rs 82 lakh on 5 Marla plans. In every one of the nine plans, it is the largest single payment. Possession is stated at 1.5 years while the plan runs for 2, so some installments may still be due after you get the keys.
Example: how one plan adds up
The 3 Marla house in Union Town Phase IV on the Bronze plan, payment by payment:
| Payment | Amount | How many | Subtotal |
| Booking | Rs 2,500,000 | 1 | Rs 2,500,000 |
| Confirmation | Rs 2,500,000 | 1 | Rs 2,500,000 |
| Monthly installments | Rs 220,000 | 24 | Rs 5,280,000 |
| Semi-annual installments | Rs 1,250,000 | 4 | Rs 5,000,000 |
| On possession | Rs 3,720,000 | 1 | Rs 3,720,000 |
| Total price | Rs 19,000,000 |
Every one of the nine plans adds up to its total price the same way, to the rupee. That matters more than it sounds. Some listings in the market quote a monthly figure, a down payment and a few balloon payments that don’t add up to the advertised price, which leaves the buyer guessing where the rest goes.
Two lessons follow. The monthly installment is not your real monthly cost, because the semi-annual and possession payments need saving for from the first month. And the plans differ in their amounts, not in how they work, which is where the Bronze, Silver and Golden tiers come in.
Barir’s Independent House Payment Plans in Union Town
Barir currently publishes three independent house options in Union Town, each with a Bronze, Silver and Golden plan: nine plans in all, on the schedule described above. The figures below come from Barir’s live payment plans as of November 2026, which also list the exact rupee amounts.
Plan Options by House Size
3 Marla independent house, Union Town Phase IV
| Plan | Total price | Booking + confirmation | Monthly (x24) | Semi-annual (x4) | On possession |
| Bronze | Rs 1.9 crore | Rs 50 lakh | Rs 2.2 lakh | Rs 12.5 lakh | Rs 37.2 lakh |
| Silver | Rs 2.05 crore | Rs 50 lakh | Rs 2.5 lakh | Rs 13 lakh | Rs 43 lakh |
| Golden | Rs 2.25 crore | Rs 50 lakh | Rs 2.8 lakh | Rs 14 lakh | Rs 51.8 lakh |
This is the lowest entry point of the three options, and the upfront amount stays at Rs 50 lakh on every tier.
3 Marla independent house, Union Town
| Plan | Total price | Booking + confirmation | Monthly (x24) | Semi-annual (x4) | On possession |
| Bronze | Rs 2.0 crore | Rs 50 lakh | Rs 2.5 lakh | Rs 12.5 lakh | Rs 40 lakh |
| Silver | Rs 2.1 crore | Rs 50 lakh | Rs 2.75 lakh | Rs 13.5 lakh | Rs 40 lakh |
| Golden | Rs 2.3 crore | Rs 60 lakh | Rs 3.0 lakh | Rs 14 lakh | Rs 42 lakh |
Barir lists two separate 3 Marla options. On matching tiers, the Phase IV house costs Rs 5 lakh to Rs 10 lakh less than this one. The Golden plan here asks Rs 60 lakh upfront instead of Rs 50 lakh.
5 Marla independent house, Union Town
| Plan | Total price | Booking + confirmation | Monthly (x24) | Semi-annual (x4) | On possession |
| Bronze | Rs 3.0 crore | Rs 60 lakh | Rs 3.5 lakh | Rs 25 lakh | Rs 56 lakh |
| Silver | Rs 3.25 crore | Rs 60 lakh | Rs 4.0 lakh | Rs 25 lakh | Rs 69 lakh |
| Golden | Rs 3.5 crore | Rs 60 lakh | Rs 4.5 lakh | Rs 25 lakh | Rs 82 lakh |
All three 5 Marla tiers share the same Rs 60 lakh upfront and the same Rs 25 lakh semi-annual payments. The difference shows up only in the monthly installment and the possession payment.
[Image: exterior photo of a Barir independent house in Union Town]
Availability changes over time, so check the available units or ask the sales team which houses are open before you plan around one.
Bronze, Silver and Golden Explained
The three tiers keep the same schedule. What changes is the total price, which rises from Bronze to Golden:
| House | Silver costs more than Bronze by | Golden costs more than Bronze by |
| 3 Marla, Union Town Phase IV | Rs 15 lakh | Rs 35 lakh |
| 3 Marla, Union Town | Rs 10 lakh | Rs 30 lakh |
| 5 Marla, Union Town | Rs 25 lakh | Rs 50 lakh |
Most of that extra cost lands on the monthly installments and the possession payment, not on the upfront amount. On the 3 Marla Phase IV house, for example, the Rs 35 lakh gap between Bronze and Golden breaks down into Rs 14.4 lakh more across the monthly installments, Rs 6 lakh more across the semi-annual installments and Rs 14.6 lakh more at possession.
What the published plans don’t say is what the higher price buys. It could be a higher finishing level, different fittings or more covered area. Until that’s clear, treat the tiers as different products, not just different payment speeds, and ask for a written specification for each tier before you choose. Barir’s Payment Plans page also says plans can be customized to your budget; the FAQ below covers what to check if you go that route.
A plan table tells you what Barir charges. It doesn’t tell you how that feels against your own monthly income, and that is where the real decision gets made.
What You’ll Actually Pay
Your budget needs three numbers: the cash you need at the start, the money you need every month, and the costs that sit outside the plan altogether.
Cash You Need Upfront
Your first big outlay is booking plus confirmation:
- Rs 50 lakh for the 3 Marla houses, on every tier except the Union Town Golden plan
- Rs 60 lakh for the 3 Marla Union Town Golden plan and all three 5 Marla plans
The booking half, Rs 25 lakh to Rs 30 lakh, goes in when you reserve the house, and the confirmation half follows (see the timing note in the step-by-step section above).
Don’t empty your savings to meet this amount. Keep a cushion for the costs listed further down, and for the first semi-annual payment, which comes around six months in.
Your True Monthly Cost
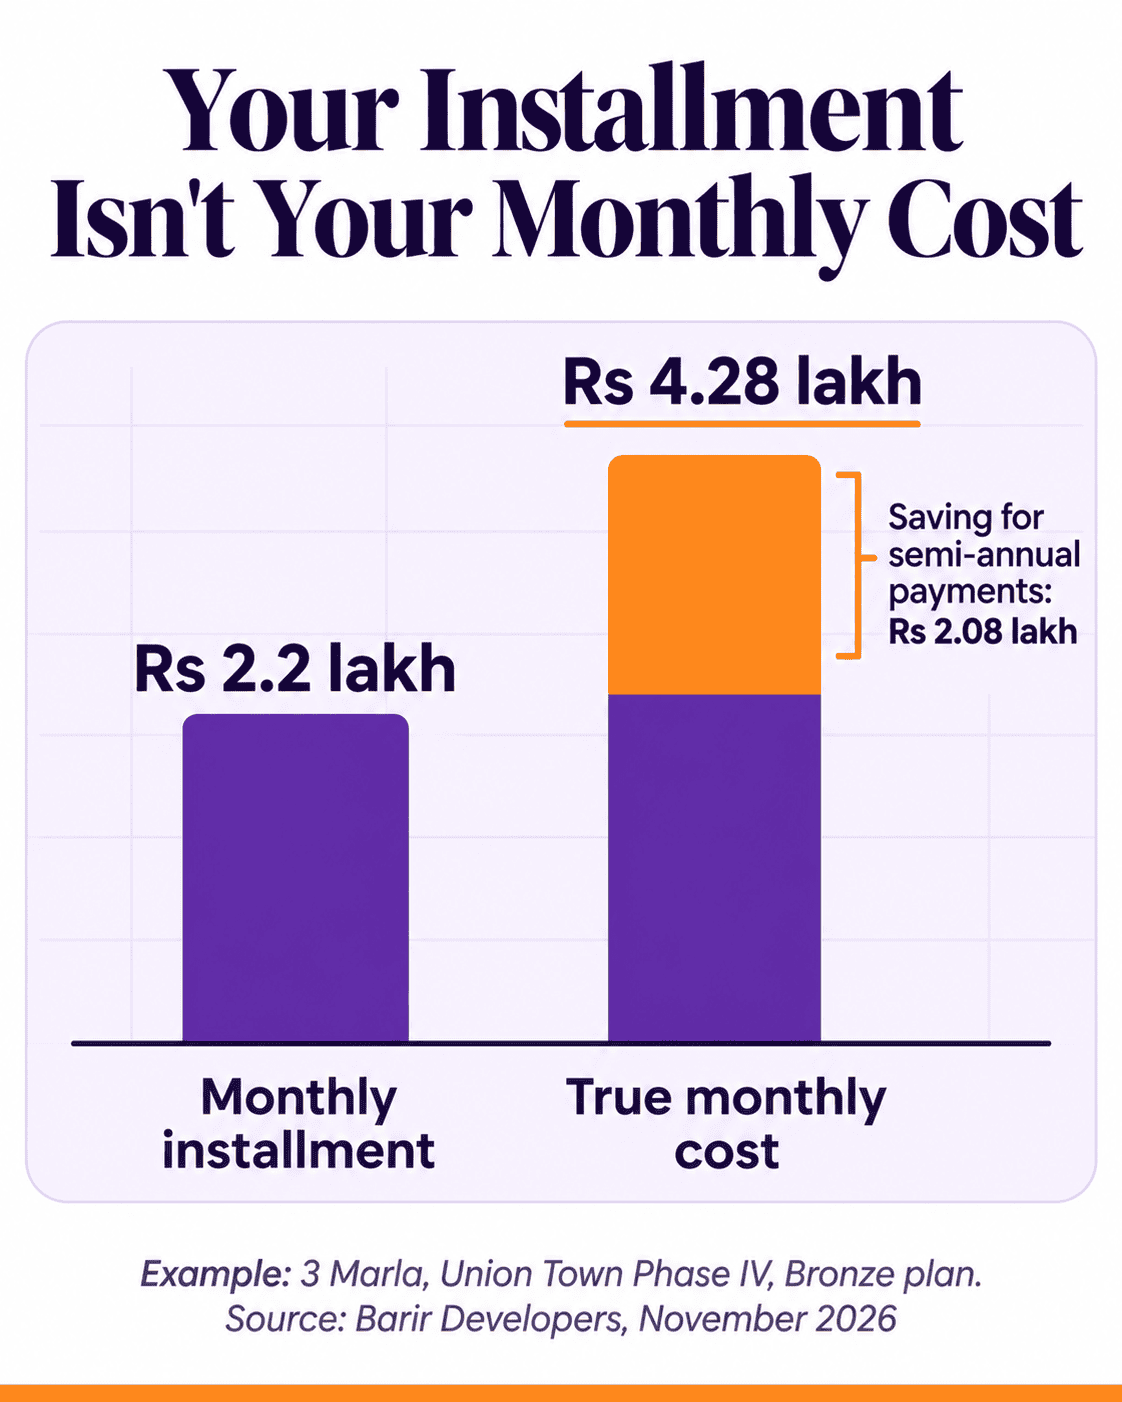
The monthly installment is the number most people look at, and it understates what you actually pay each month. Because the semi-annual payments are large, the sensible approach is to save for them every month. Add that saving to the installment and you get your true monthly cost:
| Plan | Monthly installment | Monthly saving for semi-annual payments | True monthly cost |
| 3 Marla, Phase IV, Bronze | Rs 2.2 lakh | Rs 2.08 lakh | Rs 4.28 lakh |
| 3 Marla, Phase IV, Golden | Rs 2.8 lakh | Rs 2.33 lakh | Rs 5.13 lakh |
| 3 Marla, Union Town, Bronze | Rs 2.5 lakh | Rs 2.08 lakh | Rs 4.58 lakh |
| 3 Marla, Union Town, Golden | Rs 3.0 lakh | Rs 2.33 lakh | Rs 5.33 lakh |
| 5 Marla, Bronze | Rs 3.5 lakh | Rs 4.17 lakh | Rs 7.67 lakh |
| 5 Marla, Golden | Rs 4.5 lakh | Rs 4.17 lakh | Rs 8.67 lakh |
Monthly saving = the four semi-annual payments divided by 24 months. Silver plans fall between Bronze and Golden.
The possession payment comes on top. Spread everything after the down payment across the two years and the average comes to about Rs 5.8 lakh a month on the lowest-priced plan (3 Marla Phase IV, Bronze) and about Rs 12.1 lakh a month on the highest (5 Marla, Golden). Because the possession payment falls due around the 18-month mark, you need it saved by then, not by the end of the plan.
A practical test: take your monthly take-home income, subtract fixed household costs and an emergency cushion, and compare what’s left with the true monthly cost. If the plan only works in a good month, choose a smaller house or a lower tier.
For example, a family that can comfortably set aside Rs 5 lakh a month fits the 3 Marla Phase IV Bronze plan with a small margin. A 5 Marla plan wouldn’t fit without other savings to draw on.
Costs That Aren’t in the Plan
The total price on a payment plan covers the house. It may not cover everything you pay to own and live in it. Before you book, ask the sales team whether each of these is included, and if not, what it costs:
- Transfer and registration charges when ownership moves to your name
- Taxes and duties on the purchase. Rates are set by the federal and provincial governments and change with each budget. Our breakdown of property taxes in Budget 2026-27 explains the current position
- Utility connections for electricity, gas and water
- Maintenance charges for the society after possession
- Documentation or processing fees at booking or transfer
Get the answers in writing and add them to your upfront budget. A plan that fits on paper can tip into strain once a few lakh of extra charges land at the same time as the possession payment.
Which Option Fits Your Budget?
Once the monthly number is clear, most buyers weigh two choices: an independent house or a townhouse, and if it’s an independent house, 3 Marla or 5 Marla. Barir sells all of these in the same area on the same 2-year structure, so its own plans make a fair comparison.
Independent House vs Townhouse
Here are the townhouse plans from Barir’s Payment Plans page, next to the lowest-priced plan for each independent house size:
| Barir plan | Total price | Booking + confirmation | Monthly installment | True monthly cost |
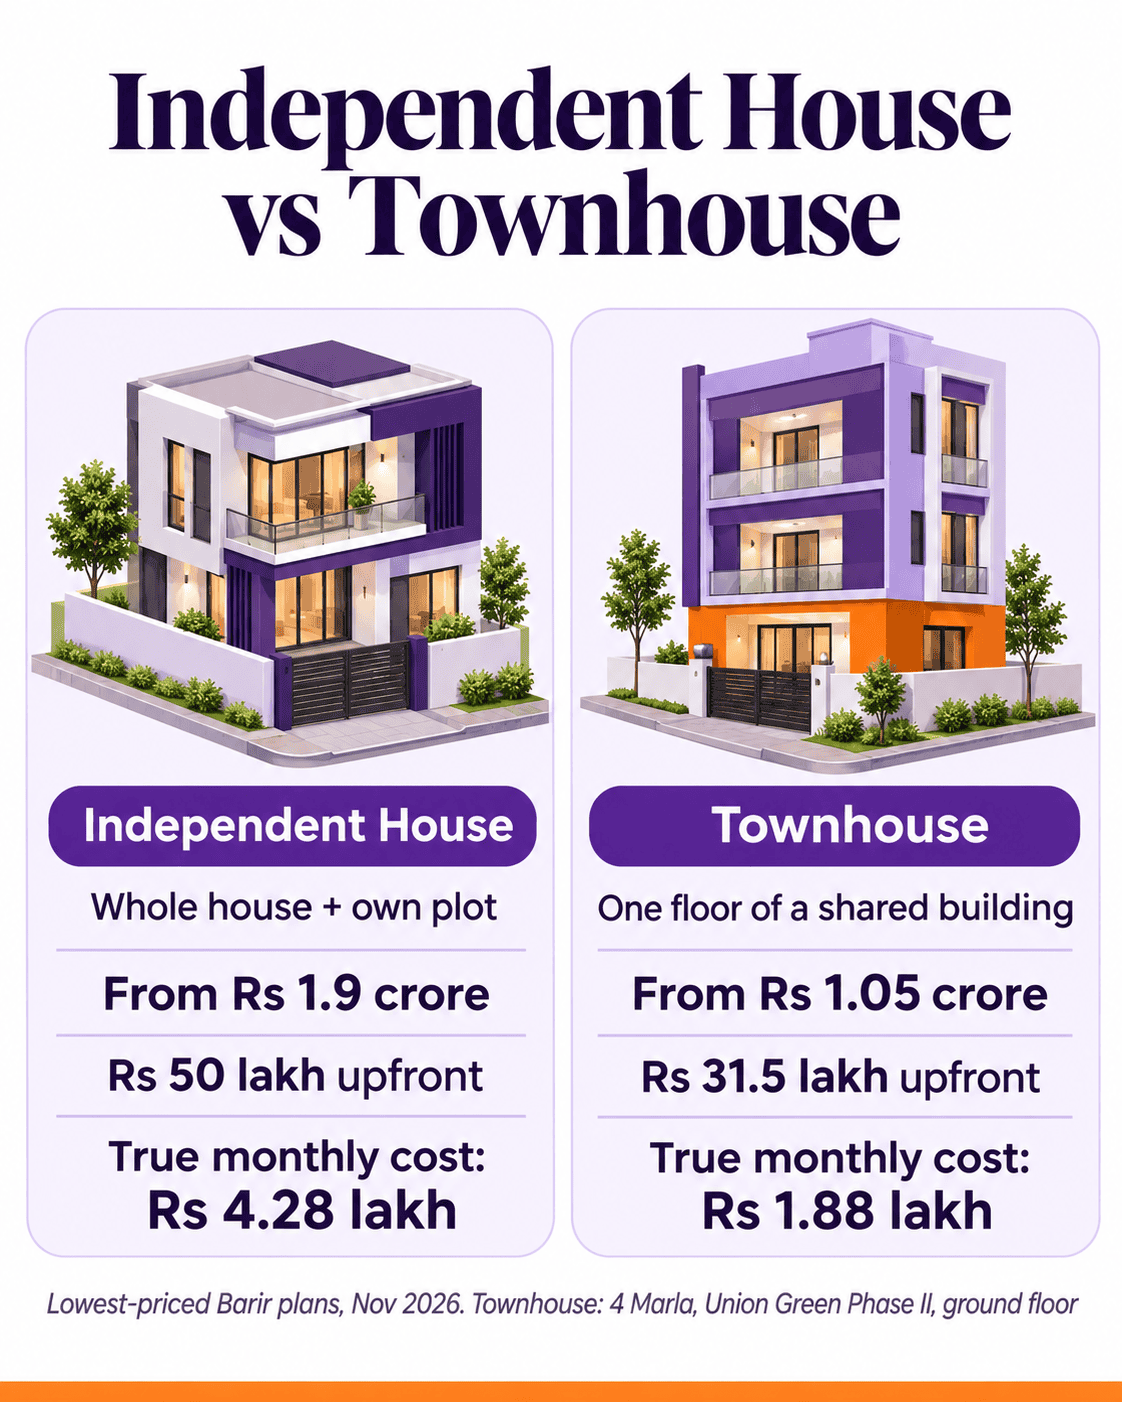
| Townhouse, 4 Marla (840 sq ft), Union Green Phase II | Rs 1.05 crore | Rs 31.5 lakh (30%) | Rs 1.05 lakh | Rs 1.88 lakh |
| Townhouse, 4 Marla (840 sq ft), Union Town | Rs 1.25 crore | Rs 37.5 lakh (30%) | Rs 1.25 lakh | Rs 2.33 lakh |
| Townhouse, 5 Marla (1,005 sq ft, 2 bedrooms), Union Town | Rs 1.45 crore | Rs 43.5 lakh (30%) | Rs 1.45 lakh | Rs 2.81 lakh |
| Independent house, 3 Marla, Union Town Phase IV (Bronze) | Rs 1.9 crore | Rs 50 lakh (26%) | Rs 2.2 lakh | Rs 4.28 lakh |
| Independent house, 5 Marla, Union Town (Bronze) | Rs 3.0 crore | Rs 60 lakh (20%) | Rs 3.5 lakh | Rs 7.67 lakh |
All five plans run for 2 years, with possession stated at 1.5 years. Townhouse figures are for the ground-floor option the page shows by default. Source: Barir Developers, November 2026.
Three things stand out:
- A townhouse asks a bigger share upfront but less money. It’s 30% of the price against 20% to 26% for an independent house, but in rupees it’s Rs 31.5 lakh to Rs 43.5 lakh instead of Rs 50 lakh to Rs 60 lakh.
- The monthly gap is wide. The lowest-priced townhouse has a true monthly cost of Rs 1.88 lakh, less than half the Rs 4.28 lakh of the lowest-priced independent house.
- You’re buying different things. A townhouse is one floor of a shared building. An independent house is the whole house and the plot it stands on, so you decide how every floor is used instead of sharing a building with other owners.
If your true monthly budget sits around Rs 2 lakh to Rs 3 lakh, a townhouse is the realistic route. Barir’s Pine Homes project offers 4 Marla townhouses and 5 Marla townhouses in Union Town, and our guide to buying a townhouse on installments explains how those plans work.
If you need a whole house for a larger family and can carry Rs 4.3 lakh a month or more, the independent house plans are the ones to compare.
3 Marla or 5 Marla?
A 5 Marla plot is two-thirds larger than a 3 Marla plot, and the price reflects it. Comparing Bronze plans:
| 3 Marla (Phase IV or Union Town) | 5 Marla | |
| Total price | Rs 1.9 crore to Rs 2.0 crore | Rs 3.0 crore |
| Booking + confirmation | Rs 50 lakh | Rs 60 lakh |
| True monthly cost | Rs 4.28 lakh to Rs 4.58 lakh | Rs 7.67 lakh |
The step up to 5 Marla costs about Rs 1 crore more in total, Rs 10 lakh more upfront and roughly Rs 3.1 lakh to Rs 3.4 lakh more every month. The published plans don’t list covered area or bedroom counts for the independent houses, so confirm both before you decide.
As a rule of thumb, a 5 Marla house suits a joint family, parents living with grown children or anyone who needs a home office. A 3 Marla house keeps the monthly cost far lower for a smaller household.
Decide by true monthly cost first and space second. A 5 Marla plan that only works with perfect months leaves no room for a delayed salary or a family emergency.
Union Town: Location, Approvals and Progress
Price and size are half the decision. The other half is whether the location, the paperwork and the pace of construction hold up.
Where Union Town Is
Union Town is a housing society in Lahore developed by Union Developers, with access from Abdul Sattar Edhi Road and Pine Avenue. Barir’s homepage describes its Pine Homes project in Union Town as 5 minutes from Bahria Town and 2 minutes from major roads.
Treat any drive time as a starting point, not a promise. Before you commit, drive from the site to your workplace, your children’s school and your family at the hours you’d actually travel.
Our complete guide to Union Town covers the society in more detail.
[Image: map of Union Town and nearby landmarks]
Approvals and NOC
Property portals describe Union Town as approved by the Lahore Development Authority (LDA), which approves private housing schemes in Lahore; buyers often call this approval the society’s NOC. Don’t take that on trust from a portal, a brochure or this article. The LDA publishes lists of approved and illegal housing schemes, so check that the society, and the phase your house is in, appear on the approved list. Then ask the developer for the approval reference and compare the two.
Two more points matter for an independent house:
- The scheme and the house are approved separately. The society’s approval covers the scheme; your house also needs an approved building plan.
- Phases can differ. Barir sells houses in Union Town and in Union Town Phase IV. An approval for one phase may not cover another, so check the phase named on your plan.
Construction Progress
Barir shares site progress on its construction updates page. Every plan states possession at 1.5 years, so compare that date with what you see on site. A house still at foundation level has far more to cover in 18 months than one whose structure is already up.
If you’re weighing a house under construction against a finished one, our comparison of off-plan and ready-to-move property in Lahore sets out the trade-offs.
[Image: recent, dated construction photo of Barir’s houses in Union Town]
Three questions to ask on your site visit:
- Which exact house is mine, and where is it on the site plan?
- What stage is it at today, and what is the written schedule to possession?
- Are roads, electricity, water, gas and sewerage connected to that street, or still pending?
Before You Book: Risks, Checks and Documents
A payment plan is a two-year commitment with large fixed payments. The time to ask hard questions is before the booking amount leaves your account, not after.
The Main Risks and How to Reduce Them
| Risk | What it looks like | How to protect yourself |
| Construction delay | Possession slips past the stated 1.5 years while your payments carry on | Ask what the agreement says if possession is late |
| Late or missed payments | A surcharge, or cancellation after repeated misses | Get the grace period, surcharge and cancellation terms in writing |
| Changes to the plan | The schedule you sign differs from the brochure | Sign only a schedule that states the total price and every due date |
| Charges outside the plan | Transfer, tax, utility and maintenance costs land around possession | Get a written list before booking (see Costs That Aren’t in the Plan above) |
| Approval gaps | The phase or the house lacks a valid approval | Check the LDA list and the approval reference before you pay |
| Needing to exit | You can’t continue the plan | Ask about refunds, deductions and whether the booking can be transferred |
Your Pre-Booking Checklist
- Verify the developer. Look at the company’s registration, track record and finished projects. Our guide on how to verify a real estate developer in Pakistan walks through each check.
- Verify the approvals for the society, the phase and the house, as described in the location section above.
- See the exact house, not a model or a render.
- Read the whole agreement, not just the payment schedule, and have a property lawyer review it.
- Pay only into the company’s official bank account, never in cash to an individual, and keep every receipt.
- Prepare your documents. Ask the sales team for the exact list. Expect to provide a copy of your CNIC, or NICOP if you live abroad, and photographs.
How to Book, Step by Step
- Pick the house and plan. Use Barir’s payment plans and your true monthly cost to shortlist one or two options.
- Confirm availability and price. Contact the sales team before you plan around a specific house, since both can change.
- Visit the site and the office. Barir’s office is at 1st Floor, 58-A, Nishter Commercial, Sector E, Bahria Town, Lahore.
- Review the paperwork. Ask for the booking form, the agreement and the full payment schedule, and take them away to read.
- Submit your documents and pay the booking amount into the company account, and get an official receipt.
- Pay the confirmation amount by the date in your schedule.
- Get written confirmation of your booking and the signed schedule, then set reminders for every monthly, semi-annual and possession payment.
For the legal side of buying in the city, see our guide to the property buying process in Lahore.
Paying From Abroad
For buyers living abroad, the plan is the same. The question is how the money gets from abroad to the builder, safely and on time.
Three Ways to Pay
| Route | How it works | What to check |
| Roshan Digital Account (RDA) | Open a Pakistani bank account online from abroad under the State Bank of Pakistan’s scheme, fund it from abroad and pay installments from it | Whether Barir accepts payments from an RDA |
| Direct remittance | Send each payment from your bank abroad, or through a licensed money-transfer service, straight to Barir’s account | Fees, the exchange rate on the day, and how receipts are issued for foreign remittances |
| Family in Pakistan | Send money to a relative who pays each installment for you | That every receipt is issued in your name as the buyer |
The RDA also opens a financing route. Under the State Bank’s Roshan Apna Ghar scheme, RDA holders can buy or finance a house in Pakistan through participating banks. Ask your bank whether it can be used for an under-construction house on a developer’s plan.
If You Can’t Be There to Sign
If you can’t travel for booking or possession, a relative in Pakistan can act for you under a power of attorney. A power of attorney signed abroad generally needs attestation by a Pakistani embassy or consulate before it can be used in Pakistan. Keep it limited to this purchase rather than signing a general power of attorney.
Two Habits That Keep Overseas Payments Safe
- Confirm account details by phone. Never send money to an account number that arrives by WhatsApp or email until you’ve confirmed it with the office on a number from Barir’s official website.
- Keep a paper trail. Save the bank’s transfer reference for every payment and match it with the receipt Barir issues.
Our guide for overseas Pakistanis buying property in Lahore covers the process in more depth.
Frequently Asked Questions
Quick answers to questions the sections above don’t cover head-on.
Can I buy a house in installments in Pakistan?
Yes. Many developers in Pakistan sell houses on installment plans: you make a down payment, then pay the rest on a fixed schedule. Barir’s independent houses in Union Town are sold on a 2-year payment plan with possession in 1.5 years. You pay a booking and confirmation amount, 24 monthly installments and 4 semi-annual installments, and a final payment at possession. Bank home finance is the other route.
Is buying a house on an installment plan safe?
It can be, if three things check out: the society and phase are approved, the developer has a track record you can verify, and the agreement states the total price, every due date, and what happens if possession is late or you need to exit. Pay only into the company’s official account and keep every receipt. The risk table above covers each point.
Can the payment plan be customized to my budget?
Barir’s Payment Plans page says plans can be customized to your budget. If you go that route, ask for the revised schedule in writing, check that every payment adds up to the total price, and confirm whether a longer or lighter schedule raises the total.
Can I pay the full price upfront or settle early?
Ask the sales team before you book whether paying in full, or clearing the balance early, earns a discount. If it does, get the discount and how it’s calculated in writing. Paying in full also removes the risk of late-payment charges, but it ties up the whole amount at once.
How many square feet is a marla?
It depends on the standard used. Many Lahore housing societies count a marla as 225 square feet, while the older revenue measure is 272.25 square feet. At 225 square feet, a 3 Marla plot is 675 sq ft and a 5 Marla plot is 1,125 sq ft. At 272.25 square feet, they’re about 817 sq ft and 1,361 sq ft.
Book a Site Visit or Download the Plan
Barir’s 3 Marla and 5 Marla independent houses in Union Town, Lahore, cost from Rs 1.9 crore to Rs 3.5 crore on a 2-year plan, with Rs 50 lakh to Rs 60 lakh upfront. Once you plan for the semi-annual payments, the true monthly cost runs from about Rs 4.3 lakh to Rs 8.7 lakh. If that fits your income with room to spare, the next step is to see the house and the paperwork for yourself.
- See the full plan: Barir’s payment plans list every house and tier.
- Book a site visit: fix a time with the sales team and go through the house and the agreement in person.
- Call: +92 322 4072868 or +92 300 7600018
- Email: barirdevelopers@gmail.com
- Visit: 1st Floor, 58-A, Nishter Commercial, Sector E, Bahria Town, Lahore
Plans and prices as published by Barir Developers in November 2026.
